

A sent e-invoice is not corrected by overwriting its Excel file and being saved as PDF again. A clear proof of correction, the clear reference to the original invoice and a suitable structured format, are crucial. The correct procedure depends on what is wrong with the invoice.
False or missing invoice information is corrected. If an invoice is to be completely cancelled, this must also be clearly documented. A subsequent price agreement is in turn something different from an already wrong price when issued.
Correct or cancel: the decision
§ 31 Paragraph 5 VATV allows the correction of missing or incorrect information by a document with a specific and unambiguous reference to the invoice. This does not lead to a general obligation to resolve any typing error by complete storno and reissue.
| Situation | Way to be clarified | What matters |
|---|---|---|
| Wrong road, actual receiver unique | Targeted correction | Correct indication and original reference |
| Wrong quantity or wrong price from the beginning | Amount adjustment or coordinated stockno with new invoice | Old and new demands must not remain double open |
| Totally wrong company as recipient | Check business incident; regularly cancel and new invoice to the actual recipient | No simple address typing error |
| The invoice is to be cancelled in full | Documenting complete storno | Initial amount fully compensated |
| Later agreed discount on original correct account | Decreasing the costs of the project | Special treatment of the reason for change and tax consequences |
The last case concerns a subsequent change in the tax base according to the § 17 UStG. A subsequent grant does not automatically make the original invoice a document which is incorrect when issued.
Example 1: Street wrong, invoice recipient correct
The fictitious invoice R-2026-104 of 2. October calls the right company, but an old street address. Performance, tax and amount are correct. A correction is R-2026-104 unique and indicates the corrected address. It explains which information is replaced; a new uncommented file with the same invoice number creates uncertainty.
The change from "Example Handel GmbH to a legally different company is not a simple road correction. Therefore, the examination begins with the order and the actual recipient of the benefit, not with the processing of the Excel cell.
If there is an e-invoice obligation, the correction must also be made in the corresponding electronic format. For the transitional periods, the B-MF under question 7b Exceptions. A purely visible change in the PDF does not correct any XML data that deviates from it.
Example 2: calculated ten hours instead of eight
The agreed net hourly rate is 80,00 Euro. Ten hours have been settled; eight are occupied. The example is 19 Percent VAT and nothing has been paid yet.
| Value | Original | Right | Reduction |
|---|---|---|---|
| Hours | 10 | 8 | 2 |
| Net amount | 800,00 € | 640,00 € | 160,00 € |
| VAT 19 % | 152,00 € | 121,60 € | 30,40 € |
| Gross amount | 952,00 € | 761,60 € | 190,40 € |
The table shows the economic effect, not a universal XML sign statement. The type of document used determines whether a correction represents the correct total amount or a reduction. A correction of the invoice via 761,60 Euro and a separate reduction via 190,40 Euro may not be booked uncoordinated in addition to the original claim.
A comprehensible alternative is the complete cancellation of the old invoice and a new invoice for eight hours, provided that this process fits the business incident and the accounting process. Both documents receive clear identifiers and a comprehensible connection. In the case of already made payment, it must be clarified whether a credit, a refund or a settlement is incurred.
Example 3: Uncheck the invoice completely
To cancel the original invoice for EUR 952.00 in full, the cancellation must offset its entire effect: EUR 800.00 excluding VAT and EUR 152.00 in VAT. The cancellation explicitly references the original invoice number and states the actual reason.
If a new invoice is subsequently issued, it depends on the facts. If a quantity is wrongly recorded, a new invoice can follow the correct amount. If a double invoice is issued, only the already correct other invoice may remain. If an order is actually returned, then the service and payment must also be considered.
Original reference, type of document and the term credit
The European accounting data model has a reference to the previous invoice: BT-25 contains its identifier; BT-26 can supplement the original invoice date. Peppol Accounting Reference Documentation shows the UBL assignment. In CII, the XML-Syntax of many ZUGFeRD invoices, the same technical information is presented differently.
A free text note alone is not a substitute for the intended structured reference. Nor does the heading "Storno, an ordinary invoice data set automatically transform into a suitable proof of correction. Type of document, amounts, tax groups and references must vote together.
The German term ‘Gutschrift’ is particularly easy to misunderstand. For VAT purposes, it refers to agreed self-billing by the recipient of the service. The legal basis is set out in § 14 Paragraph 2 UStG. A commercial credit for the reduction of a claim is not automatically the same. Also a technical credit-Note code does not define this legal classification alone.
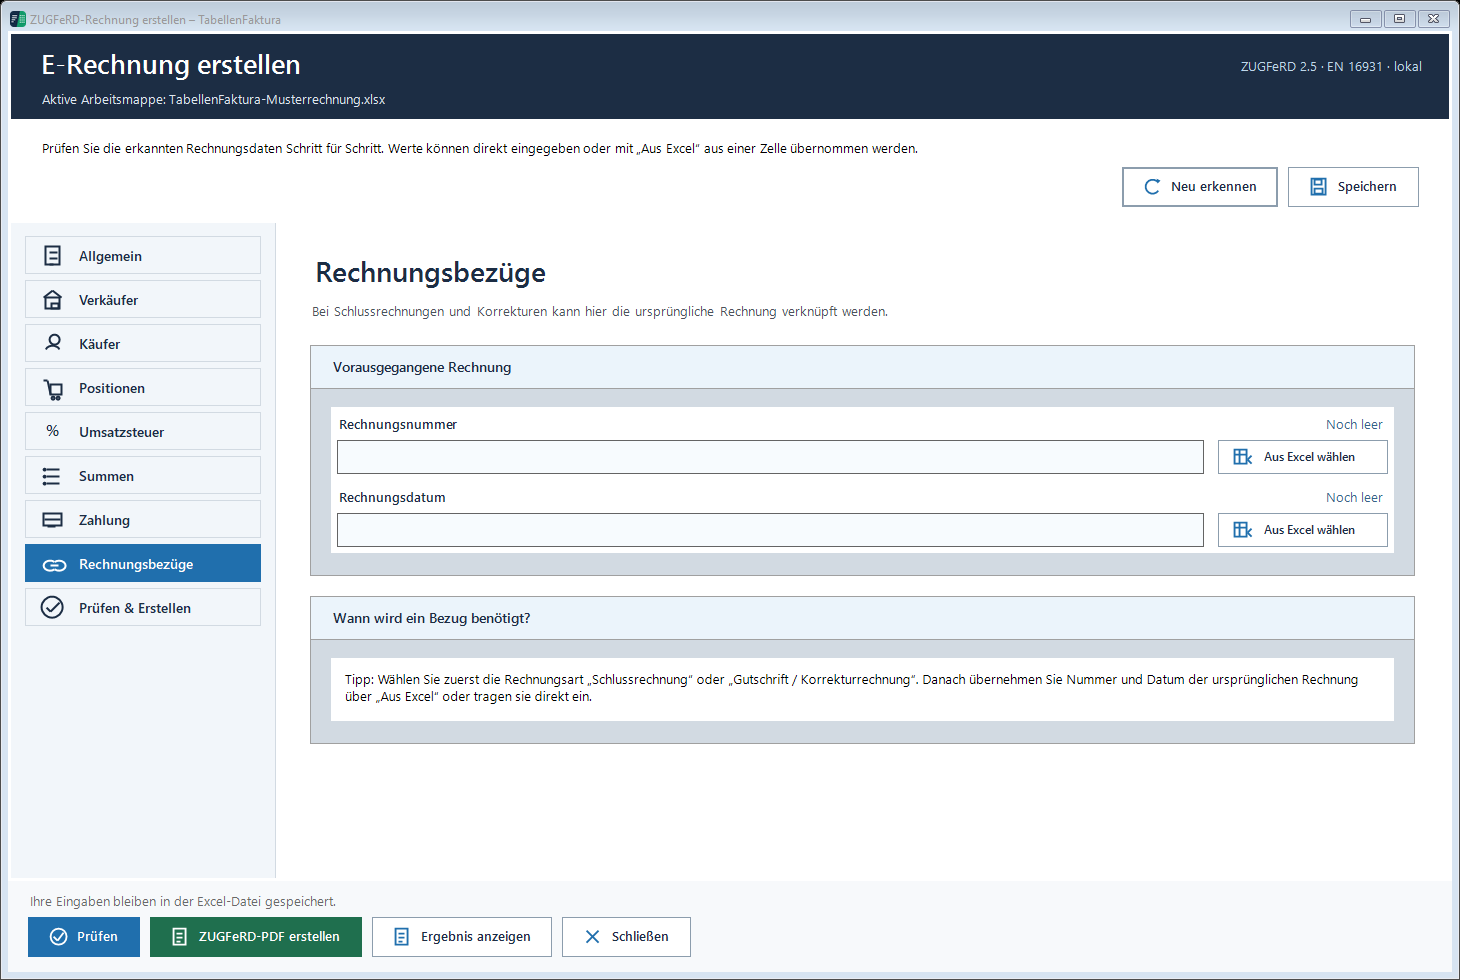
The Documentation on corrections describes the possibilities and limits in TabellenFaktura.
Prepare and check the correction in Excel
- Secure the sent status. The original file is retained; the working copy gets a comprehensible name.
- establish the reason for the change. Typing errors, wrong amount, double invoice and subsequent price changes are treated separately.
- Set the type of document and original reference. The selected export tool must actually support the required correction case.
- reconcile the amounts again. Items, tax groups, payments and the remaining entitlement are considered together.
- Check new output file. In ZUGFeRD, both the PDF presentation and the embedded XML data are compared.
- assign to the recipient and accounting records. The amount of the proof to be corrected or cancelled and the amount remaining open shall be clear.
A supported normal calculation does not yet mean that each program supports each correction method. For TabellenFaktura and other tools, the concrete evidence case must be checked before exporting. Creating ZUGFeRD invoices with Excel explains the general preparation; the instructions Open and check XRechnung helps to control structured data.
Frequently asked questions
Does any faulty e-invoice have to be cancelled?
No. Missing or incorrect information can be corrected by a document clearly related to the original invoice. The appropriate way depends on the error and the billing process used.
Is it enough to change only the PDF?
No, if the structured billing data differ. In ZUGFeRD visible representation and XML must match. An already sent document is corrected in a comprehensible way.
Can the original invoice file be overwritten?
The original invoice sent should be retained as proof. Correction and storno proofs are linked to it in a comprehensible way, rather than making the previous status unrecognizable.
Where is the original invoice number given?
The European data model provides for the reference to the previous invoice, in particular BT-25. The technical XML representation depends on the syntax used.
Is a tax bill a tax credit?
Not automatically. The VAT credit is the agreed settlement by the recipient of the benefit. A commercial reduction in receivables must be distinguished from this.